Many business owners assume the IRS will pursue the company if payroll taxes are unpaid, not them personally. The Trust Fund Recovery Penalty (TFRP) changes that assumption. It holds individuals directly liable for 100% of the unpaid payroll taxes withheld from employee paychecks.
Corporate officers, bookkeepers, accountants and anyone with payroll authority can face personal financial consequences. The IRS can assess the penalty while operations continue.
A Form 4180 interview is a key step in the TFRP assessment process, so preparation matters before the IRS makes a formal assessment.
Here’s what you need to know about the TFRP:
If you’re facing unpaid payroll taxes, professional payroll tax representation services can help you navigate the process before the IRS makes a formal assessment.
The TFRP can create personal liability for employer payroll taxes that many people don’t anticipate. More than one person within the same business can be assessed simultaneously. Two key factors determine personal liability — responsibility and willfulness.
A responsible person under IRC 6672 is someone with the duty to direct the accounting, collecting and paying of trust fund taxes. The key factor is authority and control over financial decisions. Job title doesn’t determine liability. Actual authority does.
Specific indicators from the IRS definition of a responsible person include:
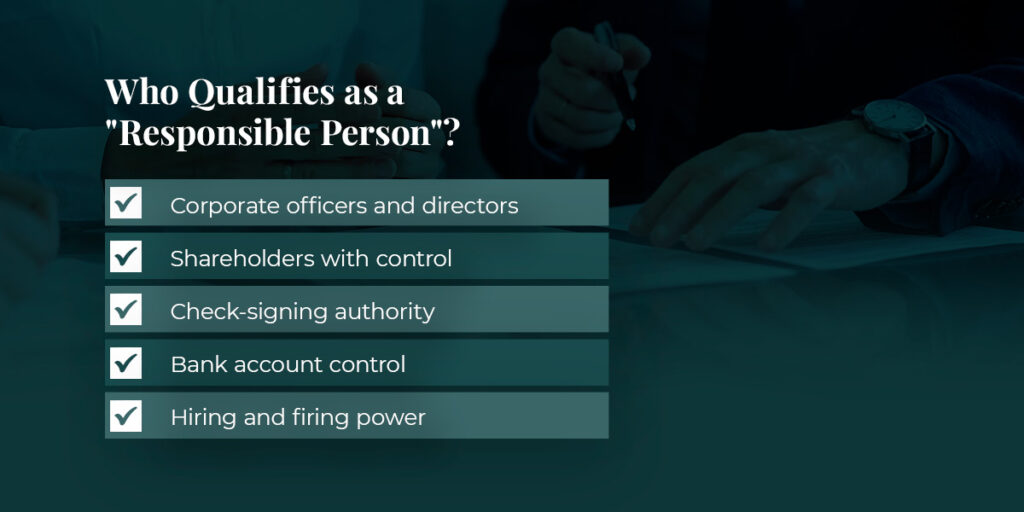
An employee whose sole function was to follow a superior’s instructions generally does not qualify. The IRS evaluates actual authority rather than job title alone. Someone who faces check signing authority tax risks can be assessed even if they didn’t own the business.
Willfulness is the second prong of TFRP liability. Willfulness does not require bad intent, fraud or deliberate wrongdoing.
A responsible person is considered willful if they were aware of unpaid trust fund taxes and paid other creditors instead. This happens frequently in struggling businesses. Management chooses to pay rent, vendors or wages while trust fund taxes go unpaid.
The requirement states that no bad motive or evil intent is needed. Using any available funds to settle other creditors if your business cannot pay employment taxes indicates willfulness.
Business owners who follow payroll tax compliance tips can help prevent these situations from developing.
Form 4180 is the formal interview tool that IRS Revenue Officers use. The interview helps the IRS evaluate whether an individual is a responsible person who willfully failed to pay. Revenue Officers conduct these interviews in person or by phone.
If you’re dealing with an IRS Form 941 payroll tax penalty, the TFRP investigation and recommendation process can put your personal assets at risk. The IRS responsible person determination process may include the Form 4180 interview, signature cards, corporate resolutions, bank records and other financial documentation.
Professional Revenue Officer representation services provide critical support during this stage.
During the interview, the Revenue Officer may ask who controlled bank accounts, signed checks, decided which creditors were paid, filed Form 941 payroll tax returns and knew the trust fund taxes were unpaid.
A Form 4180 interview creates an official case record that the IRS can use when deciding whether to recommend assessment. Because your answers may affect how the Revenue Officer evaluates responsibility and willfulness, preparation is critical when working with IRS Revenue Officers.
A formal TFRP assessment has immediate and severe consequences. Once assessed, the IRS can pursue your personal assets. Federal tax liens can attach to your property. Levies can seize your bank accounts.
The penalty may equal 100% of unpaid trust fund taxes. The IRS may continue pursuing collection against both the business and any assessed individuals. Resolution options exist for those who have already been assessed, and the IRS tax resolution options available vary based on your situation.
You can challenge assessments through the IRS Trust Fund Recovery Penalty appeals process, which provides a formal mechanism.
When the IRS proposes a TFRP assessment, it sends Letter 1153. This letter begins your appeal timeline. Acting quickly is critical because missing this deadline means the penalty becomes final.
You generally have 60 days from the date of Letter 1153 to file a protest and request an appeal with the IRS Independent Office of Appeals. You may have 75 days if the letter is addressed to you outside the U.S. If you do not file within that window, the IRS can assess the penalty and send a Notice and Demand for Payment.
Many people miss this deadline because they don’t recognize the urgency. Your options are explained in the Letter 1153 appeal rights notice.
If you cannot pay the assessed amount, the “currently not collectible” status may be an option.
Our approach focuses on complete case management rather than just filing paperwork.
Here’s what makes our process effective:
At Polston Tax, we’ve handled payroll tax cases since 2001. With over 100 years of combined tax experience, our team understands how to protect your rights during a TFRP investigation.
When you work with us, you get a tax attorney, case manager, accountant and tax preparer working together on your behalf.
Take the next step by scheduling your free consultation to discuss your case and explore your resolution options.